The Complete First-Time Home Buyer's Guide to Kitchener-Waterloo (2026 Edition) 🏡A step-by-step roadmap from your first pre-approval conversation to the day you get your keys — built around
Dated: September 23 2026
Views: 2
A step-by-step roadmap from your first pre-approval conversation to the day you get your keys — built around current Waterloo Region market data.
Sidak Chhabra, REALTOR® · Updated September 2026 · 12 min read
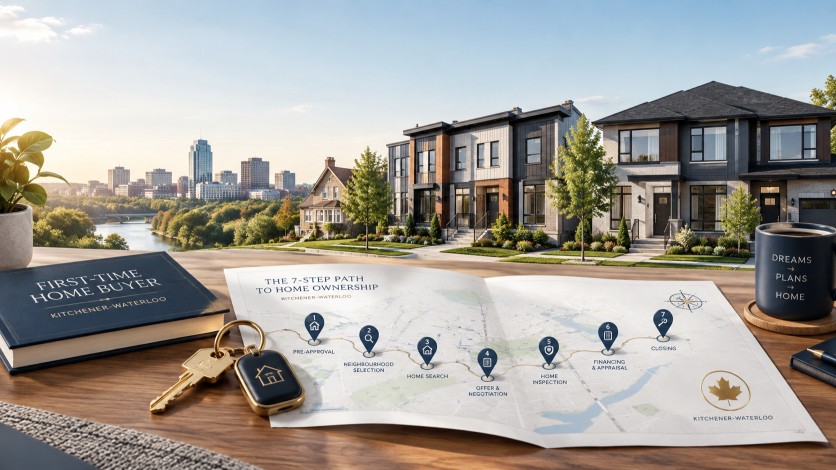
Buying your first home in Kitchener-Waterloo is exciting — but it's also a major financial, legal, and lifestyle decision. The process becomes far more manageable once you know the sequence: prepare your finances, get pre-approved, define your search area, evaluate homes carefully, make a disciplined offer, satisfy your conditions, and close with confidence.
Here's the current context: Waterloo Region's average home sale price landed at $722,683 in August 2026, with homes taking an average of 36 days to sell — up 12.5% year-over-year — according to Cornerstone Association of REALTORS®, the region's official real estate board. The more stable Kitchener-Waterloo MLS® Home Price Index benchmark sat at $628,300, down 6.0% year-over-year, while regional inventory held at 3.5 months of supply.
Translation for a first-time buyer: you have more breathing room than buyers did a few years ago, but that doesn't mean every property type or price point behaves the same way. For a closer, street-level read on where the market is heading, see Waterloo Region Real Estate: What's Really Happening This Spring and Kitchener Real Estate 2026: Budget Impact & Market Update.
Important: This article is general educational information, not legal, financial, tax, or mortgage advice. Work with a licensed mortgage professional, real estate lawyer, home inspector, insurer, and REALTOR® for guidance tailored to your specific purchase.
Before you start touring homes, it helps to understand the environment you're entering. Here's the snapshot, straight from the board's August 2026 report:
| Metric | August 2026 | Year-over-Year |
|---|---|---|
| Average sale price (Waterloo Region) | $722,683 | Down 1.0% |
| Median sale price | $680,000 | — |
| Home sales | 481 | Down 10.9% |
| New listings | 885 | Down 14.8% |
| Active listings | 1,712 | Down 10.3% |
| Months of supply | 3.5 | Down 2.8% |
| Days on market | 36 | Up 12.5% |
Broken down by city, Kitchener saw 208 sales at an average of $672,465 (down 1.0% year-over-year), Waterloo saw 104 sales averaging $712,279 (down 6.8%), and Cambridge saw 116 sales averaging $746,672 (up 5.7%). The MLS® Home Price Index benchmark — a more stable measure than the average, since averages shift with the mix of homes sold — sat at $628,300, down 6.0% year-over-year. For the latest month-by-month numbers, see the Waterloo Region Real Estate Market Report: July 2026.
Property type matters a lot here too. Condos had 7.3 months of supply (a buyer's market), while semi-detached homes had just 1.9 months of supply (a seller's market). That spread means your negotiating leverage depends heavily on what type of home you're targeting — not just the regional headline.
The first property-search decision shouldn't be "what home do I want?" It should be "what can I comfortably own?" There's a real difference between the maximum amount a lender may approve, the maximum price you could technically offer, and the monthly cost you can comfortably carry while still saving, enjoying life, and managing surprises.
Your homeownership budget should include more than the mortgage payment:
| Monthly or Recurring Cost | Examples |
|---|---|
| Mortgage payment | Principal and interest |
| Property taxes | Municipal and education portions |
| Utilities | Hydro, gas, water, internet, waste-related services |
| Home insurance | Homeowner or condo-unit coverage |
| Condo or POTL fees | Where applicable |
| Maintenance savings | Roof, furnace, appliances, plumbing, landscaping, repairs |
| Transportation | Vehicle, fuel, transit, parking, insurance |
| Lifestyle and savings | Groceries, childcare, travel, emergency fund, retirement |
A useful approach is to build three numbers: a comfortable budget that allows for savings and unexpected costs, a stretch budget that's possible but requires trade-offs, and a hard-stop number you will not exceed. Your best buying decision isn't necessarily the largest home you can qualify for — it's the home that supports your life after closing.
If property tax increases are part of your budgeting math, see How Much Will My Property Taxes Increase in 2026? And if you're weighing a condo or a freehold home tied to a common-elements corporation, don't assume every monthly fee works the same way — see POTL vs. Condo Fees in Ontario: What Buyers and Sellers Need to Know before you set your number.
This is the step almost every first-time buyer wants to skip — and shouldn't. A mortgage pre-approval gives you a working borrowing limit, helps identify documentation requirements, and may hold an interest rate for typically 90–120 days. It also signals to sellers that you're a serious, qualified buyer.
Skipping this step is the single most common reason first-time buyers waste weeks touring homes outside their real budget, then feel crushed when they can't actually get approved for the place they fell in love with. For a full breakdown of why this step comes first, read Unlock Your Dream Home: Why Mortgage Pre-Approval is the First Step.
A mortgage professional will generally review your income and employment, credit history and score, existing debt obligations, down payment source, savings and assets, estimated property taxes and condo or POTL fees, and the type of property you want to buy. Keep in mind: a pre-approval does not guarantee final financing — the lender will still need to approve the specific property and confirm your finances haven't changed.
The stress test: All federally regulated lenders must qualify you at the higher of your contract rate plus 2%, or the Bank of Canada's benchmark rate of 5.25%. If your mortgage rate is 4.14% (a current 5-year fixed rate as of September 2026), you'd need to qualify as if you were paying 6.14%.
Current down payment rules: The minimum down payment is 5% on the first $500,000 of the purchase price, and 10% on any portion between $500,000 and $1.5 million — insured mortgages now extend up to that $1.5 million price point.
What not to do after pre-approval: between pre-approval and closing, avoid financial changes that could affect your qualification — don't finance a car without consulting your mortgage professional, don't apply for unnecessary credit cards or lines of credit, don't make unexplained large deposits or withdrawals, don't change jobs or move into self-employment without confirming the impact first, don't co-sign another person's loan, and don't miss payments on any account. A mortgage approval is based on the financial picture presented to the lender — major changes can require the lender to reassess your file.
As of late September 2026, some of the best available rates in Canada sit around 4.14% for a 5-year fixed and 3.25% for a 5-year variable. The right choice depends on your risk tolerance, how long you plan to stay in the home, and your comfort with payment fluctuation.
This decision is bigger than picking whichever number looks smaller today. For the full comparison of how each option performs under different rate environments, see Fixed vs Variable Mortgage Rates in 2025: What Ontario Buyers Need to Know.
Your down payment is only part of the cash you'll need. In addition, budget for Ontario land transfer tax, legal fees and disbursements, title insurance, your home inspection, an appraisal if required, property insurance, moving expenses, utility setup, a condo status-certificate review where applicable, adjustments for prepaid taxes or condo fees, and immediate repairs, appliances, or furnishings. Closing costs typically run 1.5%–4% of the purchase price — and they draw from a different pool of money than your down payment, on a different timeline.
Ontario's land transfer tax alone can catch buyers off guard. The good news: eligible first-time buyers can receive a rebate of up to $4,000 provincially, which fully covers the tax on homes valued up to roughly $368,000. Above that threshold, you'll owe the difference. For a complete cost breakdown with saving strategies, read Closing Costs in Ontario: Full Breakdown & Savings Tips for Homebuyers.
Down payment savings tools worth knowing: the FHSA (First Home Savings Account) lets you contribute up to $8,000 per year, to a $40,000 lifetime maximum, tax-deductible, with tax-free withdrawals for a qualifying first home purchase. If you're exploring non-traditional ways to build a down payment, review the Zero Down Program carefully with a mortgage professional — borrowed down-payment strategies can increase debt obligations and aren't suitable for every buyer.
Kitchener, Waterloo, and Cambridge are not interchangeable markets. Semi-detached homes are moving fast (1.9 months of supply), while condos are sitting longer (7.3 months). Your best area depends on your commute, home type, budget, family needs, lifestyle, and future plans — start by identifying priorities across three categories:
| Category | Questions to Ask |
|---|---|
| Location | How close do I need to be to work, transit, schools, parks, family, and amenities? |
| Property | Do I need a condo, townhouse, semi, detached home, garage, parking, yard, or a legal secondary suite? |
| Lifestyle | Do I want walkability, a quieter street, proximity to universities, new development, or lower-maintenance living? |
A condo may offer a lower purchase price but include monthly condo fees. A freehold-style townhouse may carry a POTL fee for shared infrastructure. A detached home may have no monthly fee but require more direct maintenance. If you're weighing entry-level options, see Best Kitchener Neighbourhoods for First-Time Home Buyers Under $700,000.
If you have or are planning a family, proximity to strong schools has a measurable impact on both your quality of life and your home's long-term resale value. See Top-Rated Schools in Kitchener-Waterloo: A Smart Move for Your Family & Your Future for a breakdown by area.
Water, drainage, and servicing considerations should also form part of your due diligence, particularly for certain property types, older homes, or homes with unusual lot conditions. Review Water Shortage in Kitchener-Waterloo: What Homeowners & Buyers Need to Know in 2026 and ask property-specific questions before making a firm decision.
Choosing the right agent matters just as much on the buy side as the sell side — negotiation skill, local market knowledge, and responsiveness directly affect whether you get the home at the right price. This is explored fully in Why Your Choice of Listing Agent Matters in Kitchener-Waterloo, which applies to buyer representation too — the quality of guidance you get shapes your entire experience.
It's easy to become focused on cosmetic details — a renovated kitchen, stylish lighting, staged furniture. First-time buyers should learn to separate presentation from long-term value and condition. At every showing, consider lot size, layout, parking, and exterior condition; the age of the roof, windows, furnace, air conditioner, and water heater; the electrical panel and visible plumbing; signs of moisture, odour, cracking, or water damage; storage, bedroom sizes, and functional layout; basement ceiling height and renovation potential; noise, traffic, and future development nearby; property taxes and estimated utility costs; condo or POTL fees, if applicable; and whether the property fits your needs for at least several years.
After each showing, score the home before viewing the next one — location, layout, condition, monthly ownership cost, renovation needs, resale potential, deal-breakers, and emotional fit. This simple habit prevents "showing fatigue" and helps you compare properties on facts rather than the last home you toured.
With 36 days average on market and 3.5 months of supply regionally, this is not the frenzied bidding-war market of a few years ago — but it's not a free-for-all either. A strong offer isn't always the highest offer. It's one that's based on recent comparable sales, clear and complete, supported by verified financing, built around appropriate conditions, aligned with the seller's preferred closing date where possible, respectful of your maximum budget, and structured to protect you from avoidable risk.
An Ontario Agreement of Purchase and Sale commonly includes the purchase price; deposit amount and timing; irrevocable date and time; closing date; chattels included and fixtures excluded; a financing condition; a home-inspection condition; a status-certificate review condition for condominiums or POTL properties; and lawyer review or other property-specific conditions where appropriate. Your deposit demonstrates your commitment to the agreement — it's usually delivered shortly after acceptance, held in trust, and credited toward the purchase price on closing, so make sure funds are accessible before you submit an offer. A missed deposit deadline can create serious legal and practical problems.
Never waive a home inspection to "win" an offer, especially as a first-time buyer without renovation experience. An inspection can reveal foundation issues, electrical problems, roofing age, or plumbing concerns that cost tens of thousands to fix after the fact — though it's not a guarantee that no issues exist, and it doesn't replace legal or lender review. For a full walkthrough of what inspectors check and how to interpret the report, read Navigating the Home Inspection Process in Ontario: A Comprehensive Guide for Buyers and Sellers. For a condominium or POTL property, a status certificate can reveal essential financial and operational details about the corporation, including fees, reserve-fund information, rules, insurance details, litigation disclosures, and any known assessments or fee changes.
Once an offer is accepted, the work isn't over. Your key tasks typically include sending the accepted agreement to your mortgage professional immediately; completing financing due diligence before removing that condition; booking and completing the home inspection; arranging insurance (condo owners typically need their own unit policy even though the corporation insures common elements); hiring a real estate lawyer to review title, handle funds, explain closing adjustments, and register the transfer and mortgage; providing identification, down-payment funds, closing-cost funds, and insurance information to your lawyer on time; arranging utilities, movers, and address changes; and completing a pre-closing visit to confirm the home is in the expected condition and no unexpected damage has occurred.
On closing day, your lawyer completes the legal and financial transfer. Once the seller's lawyer confirms receipt of funds and the transaction is complete, keys are released according to the arrangements made — timing can vary, so avoid booking movers for the earliest possible hour or making irreversible plans before you receive confirmation that the transaction has closed. Once you have the keys: take meter readings where applicable, photograph the property's condition, change or rekey exterior locks, locate shut-off valves and the electrical panel, and start a home-maintenance file. Welcome home. 🎉
 WATCH: CLICK IMAGE
Strong first-time buyer demand doesn't just shape how buyers should approach the market — it shapes how sellers should price and position their listing, too. First-time buyers are especially active in the entry-level condo, townhouse, semi-detached, and starter-home segments, but "entry-level" doesn't mean buyers will overlook poor presentation, unclear monthly costs, deferred maintenance, or an unrealistic list price.
With inventory down 10.3% year-over-year and 3.5 months of supply across all property types in August 2026, successful sellers are focusing on preparation, pricing precision, and transparency: pricing strategically using current, highly comparable local sales; clearly disclosing property taxes, utilities, and condo or POTL fees; making documents available early for condo or POTL buyers; addressing obvious repair issues before launch; and being ready to explain recent upgrades and monthly ownership costs.
For a complete seller-preparation plan, read The Ultimate Kitchener-Waterloo Home Seller's Guide and "How to Sell Your Home Like a Pro: Mistakes Every Seller Should Avoid".
Buying your first home in Kitchener-Waterloo in 2026 means navigating a market that's cooled from its pandemic-era peak but hasn't flipped fully into buyer territory across every property type. With an average price of $722,683 and homes averaging 36 days on market region-wide, you have more time to make thoughtful decisions than buyers did a few years ago — but the fundamentals still decide whether your purchase is a smart one.
Get pre-approved first. Understand exactly what fees and taxes apply to your specific property type. Never skip the inspection. And work with professionals who know which micro-markets within Kitchener, Waterloo, and Cambridge currently favour you.
There's no single universal minimum — lenders weigh your credit score and history alongside your income, employment stability, existing debt, and down payment source. A mortgage professional can review your full file and tell you exactly where you stand before you start touring homes.
The minimum down payment is 5% on the first $500,000 of the purchase price and 10% on any portion between $500,000 and $1.5 million. Insured mortgages are now available up to that $1.5 million price point.
All federally regulated lenders must qualify you at the higher of your contract rate plus 2%, or the Bank of Canada's benchmark rate of 5.25%. A 4.14% five-year fixed rate, for example, means you'd need to qualify as if you were paying 6.14%.
Eligible first-time buyers can receive a provincial rebate of up to $4,000, which fully covers the tax on homes valued up to roughly $368,000. Above that threshold, you're responsible for the difference.
Generally, no. With Waterloo Region averaging 36 days on market in August 2026, most buyers have enough time to include this condition — waiving it can expose you to costly, hidden issues.
A traditional condo fee usually covers the building itself, while a POTL fee usually covers shared infrastructure outside a freehold home, such as private roads or visitor parking, with the owner responsible for more of their own exterior maintenance.
Your first home purchase doesn't have to feel overwhelming. A thoughtful plan turns a complex process into a series of manageable decisions — understand your budget, secure financing, choose the right location, evaluate homes carefully, make a protected offer, and close with a reliable professional team around you.
Ready to start with clarity? Book a free first-time buyer consultation with Sidak Chhabra to discuss your budget, preferred neighbourhoods, home type, timeline, and a practical step-by-step buying strategy for Kitchener-Waterloo.
Call 519-496-1300 or email chhabrasidak0513@gmail.com
Mississauga — Unit 1, 2896 Slough St, L4T 1G3 (Serving Peel Region & West GTA)
Markham — Suite 206, 3 Centre St, L3P 3P9 (Serving York Region, Durham Region & North/East GTA)
Kitchener — Suite 2B, 625 King St E, N2G 2M2 (Serving Waterloo Region)
Hamilton — Suite 300, 163 Centennial Pkwy N, L8E 1H8 (Serving Hamilton-Burlington Area)
Sidak Chhabra, REALTOR® · 519-496-1300 · chhabrasidak0513@gmail.com · la-casa.ca
Disclaimer: This article is general educational information and does not constitute financial, legal, tax, or mortgage advice. Market statistics reflect data reported by Cornerstone Association of REALTORS® as of the referenced period and are subject to change. Always consult a licensed mortgage professional, real estate lawyer, home inspector, and REALTOR® for advice specific to your situation.
“As a seasoned real estate expert serving Kitchener, Waterloo, Cambridge, Guelph, and surrounding areas, I offer a unique perspective shaped by my diverse background. Transitioning from a Commer....
The Complete First-Time Home Buyer's Guide to Kitchener-Waterloo (2026 Edition) 🏡A step-by-step roadmap from your first pre-approval conversation to the day you get your keys — built around
Ontario Homeownership Costs · 2026 GuidePOTL vs. Condo Fees in Ontario: What Buyers and Sellers Need to KnowThe listing looks like a freehold townhouse or detached home — yet it comes
📍 Serving Kitchener · Waterloo · Cambridge · Guelph 519-496-1300 · la-casa.caMarket Report · August 2026Waterloo Region Real Estate Market Report:
📍 Serving Kitchener · Waterloo · Cambridge · Guelph · London · la-casa.caOntario Mortgages · 2026 First-Time Buyer GuideYour Journey to
 Toronto Real Estate Board (TRREB); All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested
in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Royal Canadian Realty, Brokerage, Kitchener may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 23, 2026 4:50 PM UTC
Show More...

The listing data displayed is deemed reliable but is not guaranteed accurate by CREA®. Data last updated on September 23, 2026 7:23 PM UTC The trademarks REALTOR®, REALTORS®; and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA®) and identify real estate professionals who are members of CREA®. Used under license. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned by The Canadian Real Estate Association (CREA®) and identify the quality of services provided by real estate professionals who are members of CREA®. Used under license.
Show More...
 Data provided by the Ontario Regional Technology & Information Systems. The information is deemed reliable, but is not guaranteed. Not intended to solicit buyers or sellers, landlords or tenants currently under contract.
The trademarks REALTOR®, REALTORS® and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA) and identify real estate professionals who are members of CREA. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned
by CREA and identify the quality of services provided by real estate professionals who are members of CREA. Used under license.
REALTOR® contact information provided to facilitate inquiries from consumers interested in Real Estate services. Please do not contact the website owner with unsolicited commercial offers.
Show More...